
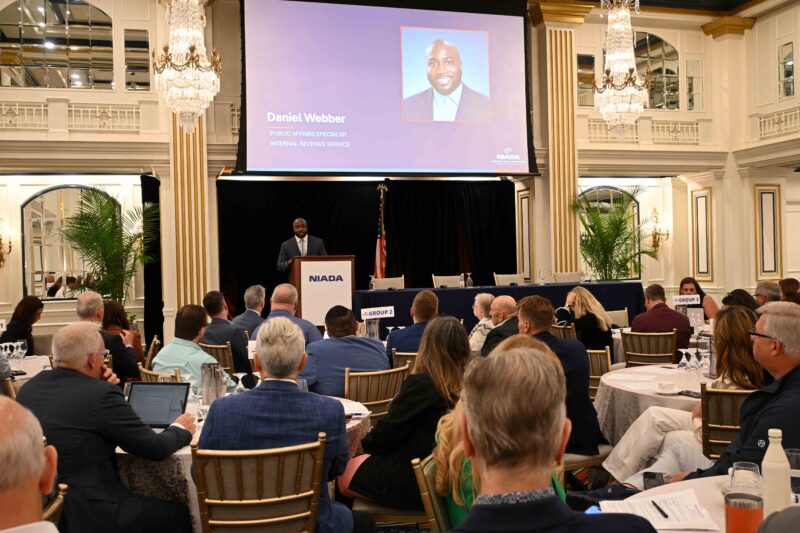
At NIADA’s National Policy Conference, the Internal Revenue Service’s (IRS) Daniel Webber walked dealers through the One Big Beautiful Bill Act one corner of the dealership at a time.
Daniel Webber, Public Affairs Specialist with the IRS, opened with a show of hands, not a slide.
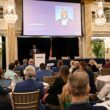
Standing before a room of independent dealers at NIADA’s National Policy Conference in Washington, D.C., on Sept. 28, the IRS representative asked how many had read the new tax laws and wondered what they actually meant for their dealership. Then, sensing a crowd that had heard more headlines than details, he put them at ease.
“I’m not taking any Social Security numbers,” he joked.
His point was a practical one. The federal tax code runs more than 70,000 pages, and nobody expects a dealer to master it. But the One Big Beautiful Bill Act, signed in July 2025, touches nearly every part of an independent dealership. So Webber spent his 20 minutes walking through the law the way a dealer might walk the property: starting in the shop and finishing at the sales desk.
The Shop
His first stop was the equipment almost every dealer has bought at some point: lifts, diagnostic tools, computers, software, and security cameras.
The law permanently restores 100% additional first-year depreciation (often called bonus depreciation) for qualifying property acquired and placed in service after Jan. 19, 2025, under Internal Revenue Code Section 168(k). Instead of spreading the deduction over several years, a dealer can write off the full cost of eligible equipment in the year it’s placed in service. The law also doubled the Section 179 deduction limit to $2.5 million, with the phase-out now starting at $4 million in qualifying purchases.
Webber framed both changes around cash flow. Money recovered sooner, he said, is money a dealer can put toward another technician, a service department upgrade, marketing, or more inventory.
The Lot
Next came a topic Webber called unique to the industry: floor plan financing. Floor plan interest has long been exempt from the federal cap on business interest deductions under Section 163(j). The new law broadens the definition of “motor vehicle” for that exemption to include trailers and campers designed to provide temporary living quarters for recreational, camping, or seasonal use and designed to be towed by or affixed to a motor vehicle.
For most independent dealers, that change won’t alter much. For those who sell towable RVs or trailers alongside cars and trucks, Webber recommended a conversation with a tax advisor. Dealers carrying other business debt may also want to ask about a related change: beginning in 2025, the overall 163(j) limit is once again calculated before depreciation and amortization are subtracted, which generally allows a larger interest deduction.
The Office
Then came another show of hands. How many in the room operated as an LLC, S corporation, or other pass-through business? Most hands went up.
For them, the news is that the 20% qualified business income (QBI) deduction under Internal Revenue Code Section 199A, which had been scheduled to expire after 2025, is now permanent. Webber said the real value is certainty. Owners can plan long-term without wondering whether the deduction will disappear in a few years. He encouraged dealers to see the change from a broader angle, too: “Legislation is now rewarding small businesses for investing in themselves.”
Then he turned to paperwork. “I don’t know one single owner that opened up a dealership because they enjoy paperwork,” he said.
For payments made after Dec. 31, 2025, the threshold for filing many Forms 1099-NEC and 1099-MISC under Internal Revenue Code Sections 6041 and 6041A rises from $600 to $2,000, with inflation adjustments to follow. The Form 1099-K threshold under Section 6050W for third-party settlement organizations returns to more than $20,000 and more than 200 transactions. Webber added a caveat he repeated more than once: “All income is taxable.” Fewer forms don’t mean less recordkeeping.
The People
Webber’s tone turned personal when he reached employees. His wife’s father and uncle owned a dealership, he said, and he saw firsthand how much keeping good people mattered to them. Finding and keeping technicians, salespeople, service advisors, and office staff, he noted, is a challenge nearly every dealership shares.
The law offers one tool for that. Starting in 2026, the amount an employee can exclude from income through an employer-provided dependent care assistance program under Internal Revenue Code Section 129 rises from $5,000 to $7,500 per year ($3,750 for married individuals filing separately). Dealers who don’t currently offer the benefit may want to ask their advisor whether it fits their recruiting and retention plans.
The Sales Desk
Webber saved customers for last. Many of them may benefit from the law’s new individual provisions, including deductions for tips, qualified overtime, car loan interest, and seniors, along with a higher standard deduction. Dealers don’t need to become tax advisors, he said, but they can become “a trusted source of information.”
His example was an older customer who needs dependable transportation to get to medical appointments but isn’t sure the purchase is affordable. For tax years 2025 through 2028, the law creates an additional deduction of up to $6,000 for taxpayers 65 and older, phasing out for those with modified adjusted gross income above $75,000 ($150,000 for joint filers). A larger refund, Webber suggested, could help with a down payment.
Dealers who plan to bring these provisions up with customers should know the limits, though.
The senior deduction reduces taxable income; it isn’t a $6,000 check. Actual savings depend on the customer’s tax situation, and seniors who owe little or no federal income tax may see little or no change in their refund.
The car loan interest deduction, worth up to $10,000 a year through 2028, applies only to new vehicles that had their final assembly in the United States, bought for personal use with a loan taken out after Dec. 31, 2024. Used vehicles don’t qualify. For independent dealers, that may be the single most important detail to get right before a customer hears otherwise.
The overtime deduction covers only the extra “half” of overtime pay required by the Fair Labor Standards Act. Because many dealership salespeople, parts employees, and mechanics are exempt from FLSA overtime requirements, dealers should check with their advisor before assuming their own employees’ overtime pay qualifies.
The Takeaway
Webber closed by bringing the room back to his central theme. “It isn’t just about the tax changes,” he said. “It’s about opportunities.”
He said the IRS will keep publishing guidance and educational resources as implementation continues, and he pointed dealers to IRS.gov and to the connection NIADA has built with the agency. For dealers, the next step is likely the same one Webber suggested throughout the session: a conversation with their tax advisor about which provisions apply to their own dealership.
This article is an editorial recap of a presentation given at the 2026 NIADA National Policy Conference. It is intended for general informational purposes only and should not be relied upon as tax, legal, or accounting advice. Remarks summarized here do not constitute official IRS guidance. Dealers should consult a qualified tax professional regarding their specific situation.